Mutual Funds: Definition, Types, Examples, Pros & Cons
If you are looking for a hands-off, long-term, diversified way to invest, mutual funds might be the answer.
The mutual fund market is huge, largely because they are a default investment for many pension plans. The term mutual fund originated in the US, but keep reading to learn the equivalent terms used in the UK and Europe.
The mutual fund market is huge, largely because they are a default investment for many pension plans. The term mutual fund originated in the US, but keep reading to learn the equivalent terms used in the UK and Europe.
QUOTE
Many financial innovations, such as the increased availability of low-cost mutual funds, have improved opportunities for households to participate in asset markets and diversify their holdings.
– Janet Yellen (former Fed Chair and US Treasury Secretary)
– Janet Yellen (former Fed Chair and US Treasury Secretary)
Big ideas
- Mutual funds offer access to a large variety of securities, such as stocks, bonds and money market instruments, across sectors. They pool investor money, which is either managed by an experienced professional or invested to track a market index.
- The benefits of mutual funds include diversification, management, and low investment minimums. However, costs have to be watched. The fund's own ongoing charge (OCF) is set by the manager and is the same wherever you buy, while platform and dealing fees depend on the provider.
- Unlike stocks and ETFs, mutual funds are priced once a day at their Net Asset Value (NAV). Orders placed before the daily cut-off are filled at the next valuation point, so there is no live price.
What is a mutual fund?
DEFINITION
A mutual fund is a professionally managed investment programme funded by shareholders that trades in diversified holdings.
The oldest modern mutual fund was launched in the US in 1924. However, it was not until the 1980s that they really became a staple of Western investment, due to major bull runs in the same decade. ETFs, a related type of fund that trades on an exchange like a stock, popularised fund investing further.
History of Mutual Funds
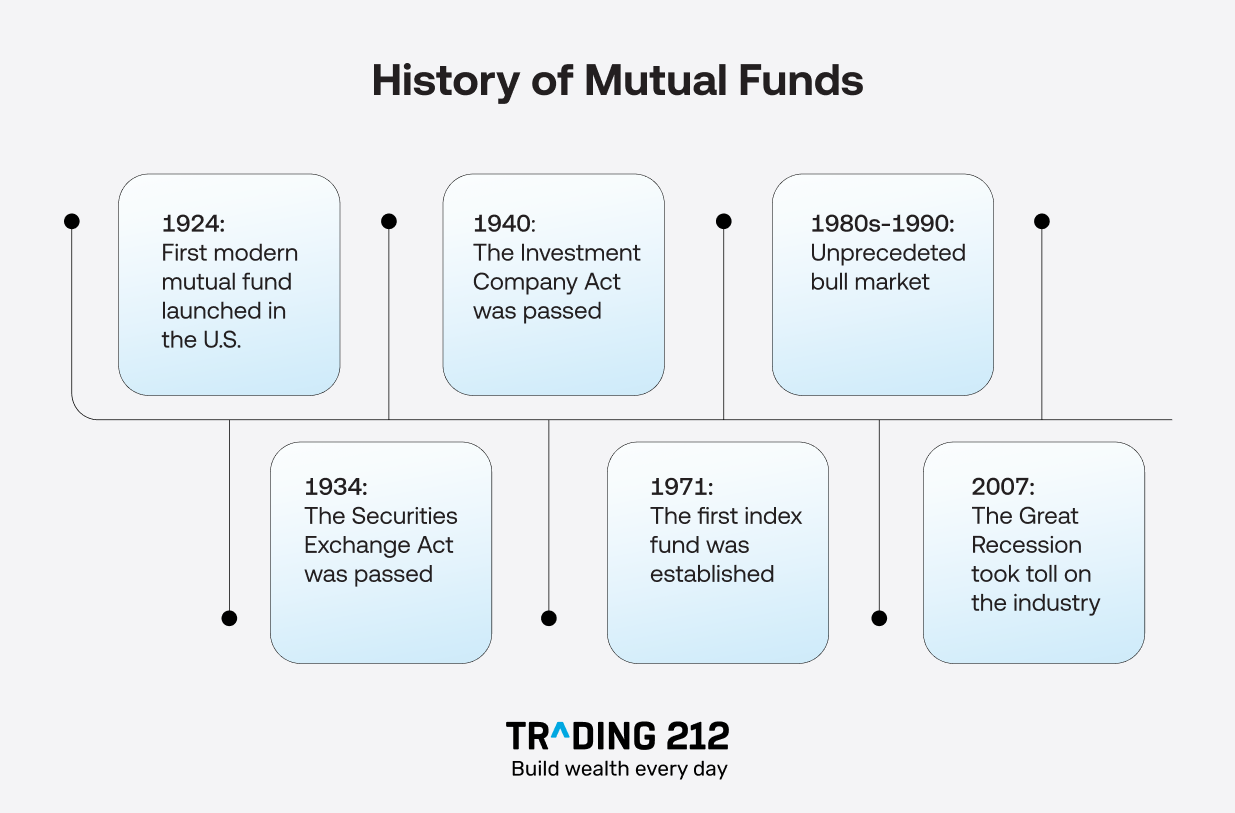
US investors hold around half of global mutual fund assets. Funds are spread across different securities, offering the benefit of diversification. This is why they are commonly used in pension plans and long-term savings.
How a mutual fund works
A mutual fund collects money from many investors and uses it to buy a group of assets, usually stocks, bonds, or both. The fund is managed by a team that follows a specific investment objective. The objective, fees and risks are set out in the fund’s prospectus and its KID or KIID.
The idea is simple. By investing in a mutual fund, you own units or shares in the fund itself, not the underlying securities directly. For example, if a mutual fund has a total NAV of £1,000,000 and 10,000 units in circulation, the NAV per unit would be £100. Owning two units would therefore represent an investment worth £200.
You can also invest steady amounts per month as opposed to buying whole units. A pension plan holder might invest £200 each month into a mutual fund over the course of many decades. The plan holder will not be looking to take profits or cut losses on a daily basis with NAV price movements. Value is tracked over time rather than minute by minute. Switching between funds is also straightforward, although each switch is processed at the next valuation point.
Mutual funds are regulated by the SEC in the US, the FCA in the UK, and by national regulators under EU rules in Europe. They must follow rules on transparency, pricing, and reporting. Most funds also publish details of their holdings regularly.
The idea is simple. By investing in a mutual fund, you own units or shares in the fund itself, not the underlying securities directly. For example, if a mutual fund has a total NAV of £1,000,000 and 10,000 units in circulation, the NAV per unit would be £100. Owning two units would therefore represent an investment worth £200.
You can also invest steady amounts per month as opposed to buying whole units. A pension plan holder might invest £200 each month into a mutual fund over the course of many decades. The plan holder will not be looking to take profits or cut losses on a daily basis with NAV price movements. Value is tracked over time rather than minute by minute. Switching between funds is also straightforward, although each switch is processed at the next valuation point.
Mutual funds are regulated by the SEC in the US, the FCA in the UK, and by national regulators under EU rules in Europe. They must follow rules on transparency, pricing, and reporting. Most funds also publish details of their holdings regularly.
How mutual funds work in the UK, Europe, and the US
In the US, mutual funds are mainly open-ended and regulated by the SEC. They price once per day after the markets close. Investors buy or sell shares directly from the fund at the NAV. Many US funds are actively managed, though index funds are also common.
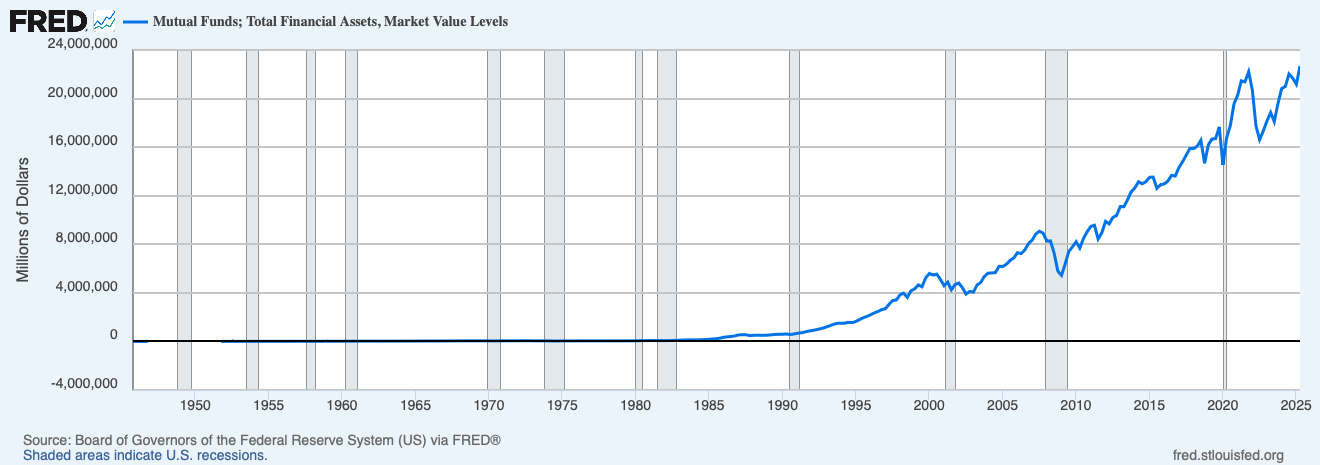 Forrás: US Federal Reserve of St. Louis
In the UK, the main types are unit trusts and OEICs. Unit trusts use a trust structure and issue units. OEICs are corporate structures that issue shares. Both are open-ended and priced daily. They are regulated by the FCA. UK funds often focus on income or growth and usually offer two share classes: Accumulation (Acc), which reinvests income, and Income (Inc), which pays it out.
Feature | US | UK | Europe |
Common name | Mutual fund | OEIC or unit trust | SICAV or FCP |
Legal form | Open-end investment company | Company (OEIC) or trust (unit trust) | Company (SICAV) or contractual fund (FCP) |
Main rules | Investment Company Act 1940 | UK UCITS or NURS | UCITS or AIF rules |
Regulator | SEC | FCA | National regulators (e.g. CSSF in Luxembourg, Central Bank of Ireland) |
Pricing | Once a day at NAV | Once a day at NAV | Usually once a day at NAV |
Usual currency | US dollars | British pounds | Euros, often other currencies too |
In Europe, open-ended funds are usually set up as a SICAV (a company with variable capital) or an FCP (a contractual fund, similar to a unit trust). Most funds sold to retail investors follow UCITS, a set of EU rules on diversification, liquidity and disclosure that lets a fund be sold across EU countries. Many UK OEICs and unit trusts follow equivalent UK UCITS rules.
Types of mutual funds with examples
Mutual funds fall into four basic types:
- Equity
- Fixed income
- Balanced
- Money market
Equity funds invest mainly in stocks. They aim for growth. These funds can focus on certain sectors, regions, or styles (like value or growth). Returns depend on the stock market.
EXAMPLE
An example of an equity OEIC in the UK is the Invesco UK Equity Income Fund. It invests mainly in UK companies, and the fund manager picks individual stocks rather than tracking an index.
Like most UK funds, it is available in different share classes, including accumulation (Acc), which reinvests income, and income (Inc), which pays it out. Its ongoing charges figure (OCF), along with any entry charges or dilution adjustments, is set out in the fund’s KID or KIID.
Past performance is no guarantee of future results. This information is not investment advice. Do your own research. This example is for educational purposes only.
Like most UK funds, it is available in different share classes, including accumulation (Acc), which reinvests income, and income (Inc), which pays it out. Its ongoing charges figure (OCF), along with any entry charges or dilution adjustments, is set out in the fund’s KID or KIID.
Past performance is no guarantee of future results. This information is not investment advice. Do your own research. This example is for educational purposes only.
Fixed income funds put money into bonds and other debt. These funds try to provide regular income, usually with lower price swings than equity funds. They are generally considered lower risk, though not risk-free.
Balanced funds mix stocks and bonds in one fund. The mix can vary depending on the fund's goal. Some lean more toward growth, others toward income. The fund’s KID or KIID and prospectus explain its objective, risks and costs.
Balanced funds mix stocks and bonds in one fund. The mix can vary depending on the fund's goal. Some lean more toward growth, others toward income. The fund’s KID or KIID and prospectus explain its objective, risks and costs.
EXAMPLE
The Fidelity Multi Asset Income Fund is an example of a balanced OEIC in the UK. It invests across a mix of asset classes, including stocks, bonds and alternative investments, aiming to provide income with some capital growth over time.
Its ongoing charges figure (OCF), transaction costs and any entry or dilution charges are set out in the fund’s KID or KIID.
Past performance is no guarantee of future results. This information is not investment advice. Do your own research. This example is for educational purposes only.
Its ongoing charges figure (OCF), transaction costs and any entry or dilution charges are set out in the fund’s KID or KIID.
Past performance is no guarantee of future results. This information is not investment advice. Do your own research. This example is for educational purposes only.
Money market funds (MMFs) invest in short-term debt, such as Treasury bills and commercial paper. They aim to keep the price stable while giving modest returns. They are generally among the lower-risk fund types, but their value can still fall.
Mutual fund categories
While there are four major types of mutual funds, there are many more variants and subcategories. The different variants are outlined in the table below.
Mutual fund type | Description | Pros | Cons |
Equity | Invest mainly in company stocks. | Higher return potential. Good for long-term growth. | More price swings. Sensitive to market moves. |
Bond | Invest in government or corporate debt. | Regular income. Usually less volatile than stocks. | Interest rate risk. Lower growth over time. |
Index | Low fees. Broad market exposure. | No manager decisions. Follows the index exactly. | |
Multi asset | Combine stocks, bonds, and other assets. | Built-in diversification. Balanced risk. | Less control over asset mix. Can be complex. |
Money market | Invest in short-term debt like T-bills or cash. | Lower price swings. Easy to access. | Low returns. Can lag inflation. |
Income | Focus on assets that pay dividends or interest. | Steady payouts. Can support income needs. | Limited growth. Can be sensitive to rate changes. |
Target date | Adjust mix of assets based on a future date (like a retirement year). | Hands-off. Shifts automatically over time. | Less flexible. Allocation may not fit every investor. |
Balanced | Hold a fixed ratio of stocks and bonds. | Simple way to stay diversified. | No customisation. Allocation may not suit every market cycle. |
International | Invest in non-domestic companies or markets. | Exposure to global growth. Currency benefits possible. | Currency risk. Foreign markets can behave differently. |
Sector/Theme | Focus on one industry (like tech) or theme (like clean energy). | High potential if the sector does well. | Can be volatile. Less diversified. |
Socially responsible | Choose assets based on ESG criteria (environment, social, governance), or on faith-based screens such as Shariah-compliant funds. | Aligns with values. Gaining popularity. | Limited choices. May miss some profitable sectors. |
Are there drawbacks to mutual funds?
Despite mutual funds being a hugely popular investment option, it is always useful to stand back and see the other side of public opinion. Critics of mutual funds highlight the high fees and lack of flexibility.
QUOTE
Most investors will be better off buying a low-cost index fund.
— Warren Buffett (on mutual fund management fees)
— Warren Buffett (on mutual fund management fees)
Another common criticism is that mutual funds often underperform the market due to these fees and the challenge of consistently picking winning stocks. John Bogle, founder of Vanguard, also criticised actively managed funds, noting that the majority of actively managed funds underperform their benchmarks.
Mutual funds lack the ability to react quickly to market changes because they are priced only once a day. Orders placed before the cut-off are filled at the next valuation point, so you will not know the exact price when you place the order. Lastly, outside a tax wrapper such as an ISA or SIPP, gains and income from mutual funds may be subject to UK capital gains and dividend tax.
Mutual funds lack the ability to react quickly to market changes because they are priced only once a day. Orders placed before the cut-off are filled at the next valuation point, so you will not know the exact price when you place the order. Lastly, outside a tax wrapper such as an ISA or SIPP, gains and income from mutual funds may be subject to UK capital gains and dividend tax.
Recap
In a market full of investment choices, mutual funds remain a structured and widely used option. Still, like any financial product, their value depends on how well they match your personal goals.
This is why the most important item to keep in mind is what your goals are – once you are clear on what you want, there could be thousands of financial products that meet the criteria.
Once you understand an investment in its entirety – taxes, costs, risks, rewards – then you can make a clear decision. After this, it just takes time, patience, and dedication to see results.
This is why the most important item to keep in mind is what your goals are – once you are clear on what you want, there could be thousands of financial products that meet the criteria.
Once you understand an investment in its entirety – taxes, costs, risks, rewards – then you can make a clear decision. After this, it just takes time, patience, and dedication to see results.
FAQ
K: What are the 4 types of mutual funds?
The four main types of mutual funds are equity funds, fixed-income funds, money market funds, and balanced funds.
Equity funds invest mostly in stocks.
Fixed-income funds focus on bonds.
Money market funds go into short-term debt.
Balanced funds mix stocks and bonds. Each has its own mix of risk and return.
Equity funds invest mostly in stocks.
Fixed-income funds focus on bonds.
Money market funds go into short-term debt.
Balanced funds mix stocks and bonds. Each has its own mix of risk and return.
K: How do mutual funds work?
A mutual fund pools money from many people and invests it in stocks, bonds or other assets, either chosen by a fund manager or set to track a market index. You buy units or shares in the fund. If the value of the fund’s investments goes up, your holding goes up in value, and you can also earn from dividends or interest. Mutual funds are priced once a day, so orders are filled at the next valuation point.
K: What is the equivalent of mutual funds in the UK?
In the UK, mutual funds are called unit trusts and open-ended investment companies (OEICs). Both pool money from many investors and spread it across many holdings. They are run by fund managers. The structure and rules are slightly different, but the main idea is the same as mutual funds. In Europe, the closest equivalents are SICAVs and FCPs.
K: Are mutual funds safe?
Mutual funds carry different levels of risk depending on what they invest in. Money market funds tend to be more stable. Equity funds can move up and down more. A fund’s performance depends on the market and on the manager’s choices, or the index it tracks. Prices can go down as well as up, so you could get back less than you invest.
K: Is an ETF a mutual fund?
Both are types of investment funds, but they work differently. An ETF trades on a stock exchange like a share, with a live price during market hours. A mutual fund is priced once a day at NAV, and orders are filled at the next valuation point. Most ETFs track an index, while mutual funds can be active or passive. Both spread your money across many investments.
K: What is the difference between open-ended and closed-end funds?
Open-ended funds issue and redeem units or shares at the NAV, based on investor demand. Their supply is not fixed. Closed-end funds, such as UK investment trusts, issue a fixed number of shares that trade on an exchange like stocks. Their price can differ from the NAV based on market demand.